

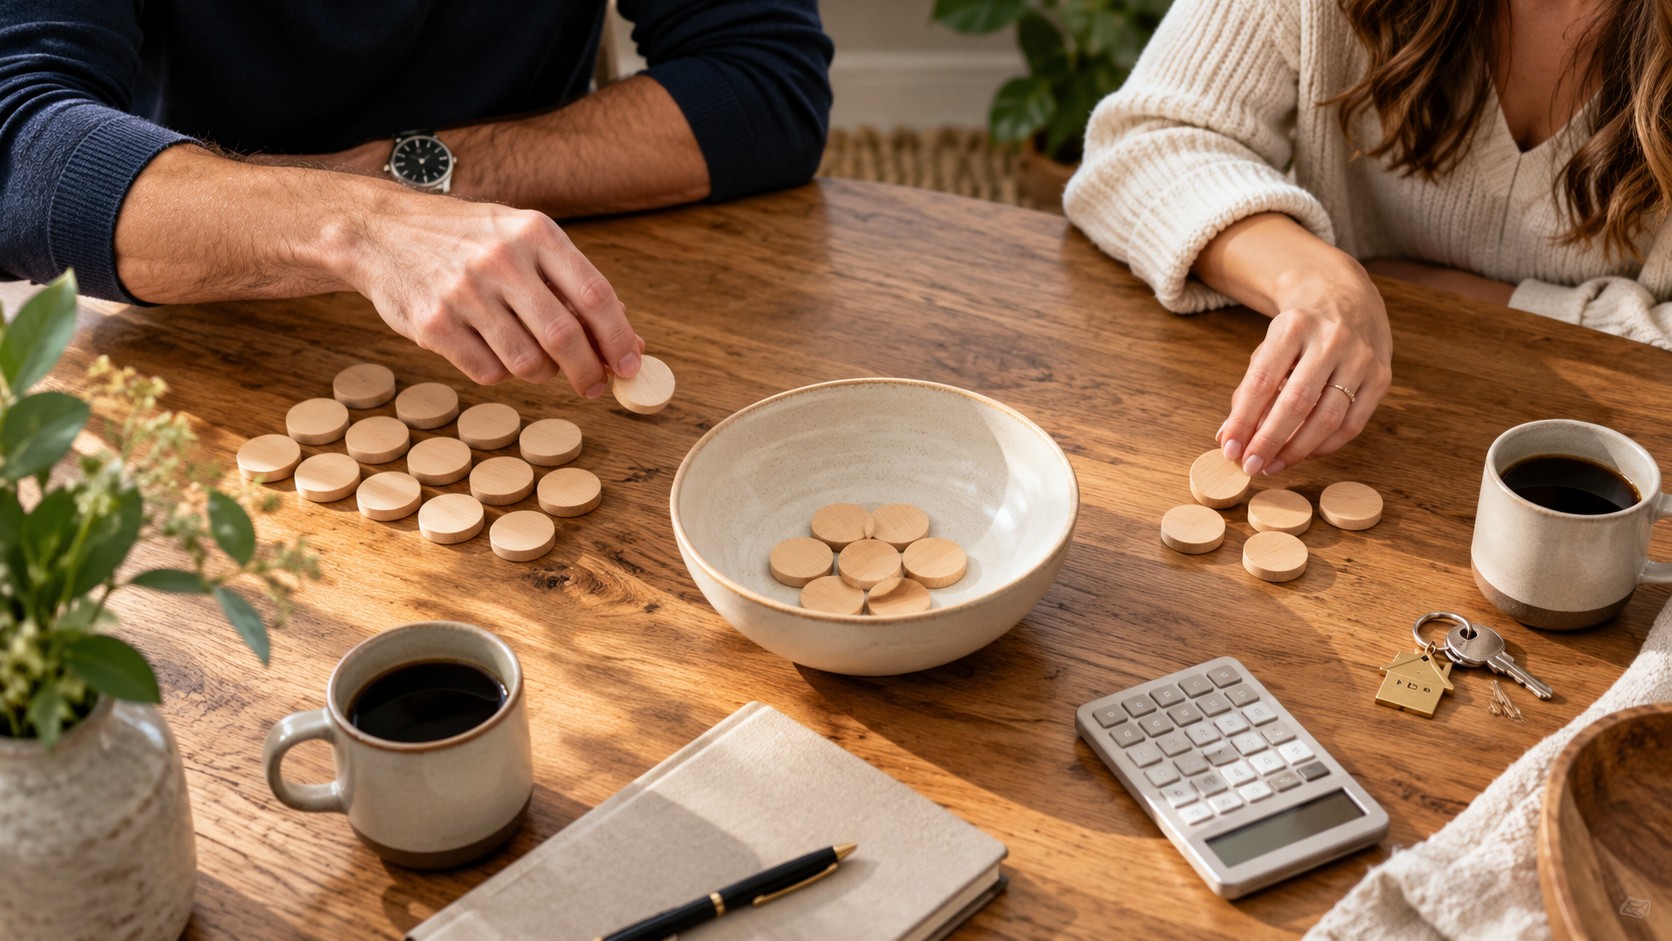
Proportional expense splitting is an equitable financial strategy where partners in a committed relationship contribute to shared living expenses based on their respective percentage of household income, rather than dividing costs equally 50/50. In a January 2026 survey of 1,400 U.S. adults in committed relationships, Mercury's New Economics of Modern Love report found that Gen Z respondents were more than three times as likely as baby boomers to split bills proportionate to income (17% versus 5%). The practice is not limited to younger couples, but the finding shows how quickly the model is spreading among the next generation of high earners. This framework preserves discretionary saving capacity for both partners and establishes clear groundwork for prenuptial asset protection when navigating disparities in W2 earnings or family trust assets.
For accomplished singles, financial alignment is rarely about finding someone with the exact same net worth down to the dollar. It is about emotional security, lifestyle pacing, and mutual respect. When one partner earns $450,000 as a corporate executive while the other earns $180,000 as an established consultant, an arbitrary 50/50 split either forces the lower earner into unsustainable spending or restricts the household lifestyle. Proportional splitting bridges this gap with mathematical fairness.
The Flaws of the 50/50 Model for High-Income Partners
The traditional 50/50 split was conceived in an era of uniform cost-of-living structures and modest discretionary budgets. In modern metropolitan markets—such as New York, San Francisco, Miami, or Los Angeles—luxury leases, private dining, international travel, and private investments command substantial capital.
When high-income couples default to a rigid 50/50 split, predictable challenges emerge:
- Lifestyle Friction: The partner with higher cash flow naturally gravitates toward premium housing and premier travel experiences. Splitting these 50/50 places an asymmetric financial burden on the partner with lower baseline income, depleting their personal retirement and investment accounts.
- Resentment and Power Imbalances: Forcing a lower-earning partner into 50/50 living costs can breed quiet financial anxiety. Conversely, if the higher earner subsidizes everything unilaterally without a clear framework, feelings of entitlement or resentment can undermine emotional intimacy.
- Loss of Individual Financial Autonomy: High-achieving singles cherish their hard-won financial independence. A proportional structure ensures that after household commitments are settled, both partners retain autonomous capital to invest, support philanthropic causes, or spend as they see fit.
Financial Architecture Comparison: Evaluating Modern Relationship Models
High-net-worth and HENRY couples typically consider three primary financial operating models:
| Financial Model | Structural Mechanics | Equity & Fairness | Asset Protection & Autonomy | Suitability for High Earners |
|---|---|---|---|---|
| Rigid 50/50 Split | All shared living costs divided strictly in half, regardless of income disparity | Poor: Penalizes the lower-earning partner and restricts household lifestyle pacing | Moderate: Keeps individual accounts separate, but creates lifestyle drag | Low: Often strained when income levels differ sharply |
| Proportional Income Split | Shared expenses calculated based on percentage contribution to combined net income | High: Equalizes the relative effort of living costs while preserving personal savings | High: Maintains distinct separate accounts alongside a single joint operating fund | Optimal: Ideal for dual-career professionals, HENRYs, and modern partnerships |
| Complete Asset Pooling | All earnings, bonuses, and assets deposited directly into a single combined account | Neutral: Eliminates calculation friction, but erodes individual financial boundaries | Low: Blurs pre-marital separate property and creates vulnerability during dissolution | Niche: Suitable for traditional single-income marriages, but risky for high-asset singles |
Managing the Trust Fund Dynamic: When W2 Earnings Meet Generational Capital
In affluent social circles, couples frequently navigate situations where high earned W2 income meets inherited generational wealth, family business equity, or irrevocable trust distributions. Consider a hypothetical example: a high-earning professional (earning $350,000 annually) dating an heir to a substantial family trust ($5,000,000+).
Navigating this dynamic requires distinguishing between liquid cash flow and corpus capital:
1. Separate Corpus from Daily Cash Flow
Inherited trusts typically generate passive dividend yields or maintain mandatory disbursement structures. High-earning couples maintain healthy dynamics by pegging proportional living contributions to distributable annual income rather than total underlying asset net worth.
2. Protecting Separate Pre-Marital Assets
Family trusts often carry fiduciary requirements protecting capital from commingling. Couples who establish proportional operating accounts early find the transition to formal prenuptial agreements seamless because clear accounting boundaries already exist.
3. Clear Prenup Alignment as Relationship Due Diligence
Rather than viewing a prenuptial agreement as a lack of romantic faith, modern high-earning singles treat prenups as sound corporate due diligence. A well-crafted prenup delineates separate pre-marital property, confirms trust protections, and formalizes how joint marital contributions will be divided if the relationship changes.
The 4-Step Proportional Operating Playbook
To implement proportional financial architecture with minimal friction, accomplished couples rely on a structured four-step methodology:
- Calculate Net Combined Operating Income: Tally each partner's predictable net take-home pay (after taxes, 401(k) deductions, and health premiums). For instance, Partner A earns $20,000 monthly (67%) and Partner B earns $10,000 monthly (33%). Combined monthly net income is $30,000.
- Establish a Dedicated Joint Household Account: Open a shared checking account dedicated strictly to agreed-upon collective expenses: mortgage/rent, utilities, shared groceries, joint travel, and routine household maintenance.
- Fund the Joint Account Proportionately: If shared household costs total $12,000 per month, Partner A transfers $8,040 (67%) and Partner B transfers $3,960 (33%).
- Retain Absolute Autonomy Over Remaining Funds: The remaining discretionary income ($11,960 for Partner A, $6,040 for Partner B) remains in their separate personal checking and brokerage accounts. Neither partner requires permission from the other to invest, save, or spend their remaining funds.
Cultivating Authentic Compatibility on Luxy
Financial transparency is not an uncomfortable conversation to be postponed until engagement—it is a cornerstone of authentic compatibility. When accomplished singles date with clear intentions and aligned life standards, discussing financial architecture becomes a source of connection rather than contention.
On Luxy, members join a curated ecosystem designed specifically for accomplished, high-standard singles. Through optional income verification and a strict 24-hour profile vetting process, Luxy helps reduce the risk of financial misrepresentation. Members enter relationships knowing that their peers share comparable career drive, lifestyle pacing, and mutual respect.
Explore our related research on financial compatibility vs. chemistry, high-earning prenups and due diligence, and dating for marriage to build a lasting relationship grounded in mutual respect and financial clarity.
Frequently Asked Questions
What qualifies someone as a HENRY in modern dating?
HENRY stands for High Earner, Not Rich Yet. It is commonly used to describe professionals with high salaries and strong earning potential who have not yet accumulated substantial net worth, often because of student loans, high taxes, or early-stage equity vesting. The term is informal, and the income range it implies varies by city and social circle.
Should couples split bonuses and variable equity proportionately?
A common approach is to keep annual performance bonuses, restricted stock units (RSUs), and equity distributions separate unless they are dedicated toward a mutually agreed joint goal, such as purchasing a primary residence. Base routine household living expenses on predictable baseline monthly cash flow.
Does proportional expense splitting complicate prenuptial agreements?
On the contrary, proportional expense splitting simplifies prenuptial drafting. By keeping individual investment accounts separate and funding a joint account solely for living expenses, couples establish a clean paper trail that prevents the unintentional commingling of pre-marital separate property.
LUXY JOURNAL